As soon as you experience a covered loss or damage to your home, contact your insurance company's claims department. This is usually done by phone or online.
During your first contact, you will need to provide basic information, including your policy number, the date and cause of the loss, and a general description of the damage.
The insurance company will assign a claims adjuster to your case. This adjuster will be responsible for assessing the damage and guiding you through the claims process.
It's crucial to document the damage with photographs and written descriptions. Make a list of damaged or lost items. Keep receipts and records related to repairs or replacements.
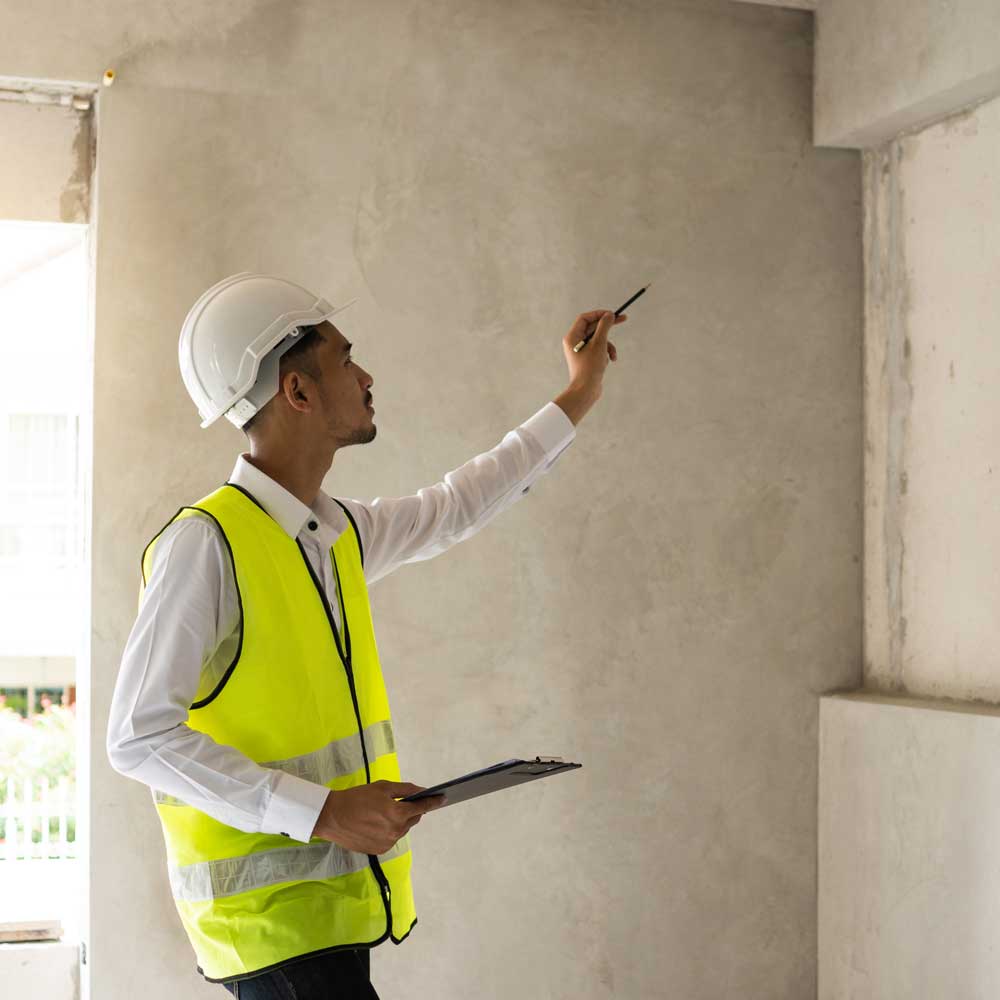
The adjuster will schedule an inspection of your property to assess the extent of the damage. Be prepared to show them the damaged areas and provide any relevant documentation.
The adjuster will review the information and documentation to determine the validity of the claim and assess the cost of repairs or replacements.
Once the assessment is complete, the insurance company will provide you with a settlement offer. This offer may cover the cost of repairs, replacements, or other covered expenses.
If you believe the settlement offer is insufficient or was denied altogether, RT Loss Management Group will negotiate your maximum settlement.
If you agree to the settlement, you'll typically receive a check or electronic payment for the approved amount. You may also receive separate payments for structural damage and personal property losses.
You can use the settlement funds to repair or replace the damaged items or structures. It's important to follow the terms and conditions outlined in your policy.
The insurance company may conduct a final inspection to ensure that repairs were completed as agreed upon.
Once all repairs are satisfactory, and the claim is settled, your claim will be officially closed.
After making a claim, your insurance company may adjust your premium or terms, depending on the circumstances and the terms of your policy.